Florida Amendment 3 Passed: What It Means for Your Primary or Second Home
Florida voters approved Amendment 3 on November 3, 2026, changing how property taxes will work for both homesteaded and non-homesteaded properties beginning January 1, 2027.
But the change isn't the same for everyone.
If Florida is your primary residence, the amendment significantly increases the homestead exemption that applies to non-school property taxes.
If you own a second home, rental property or other non-homestead property in Florida, you won't receive the larger homestead exemption, but another part of the amendment may benefit you: the annual cap on increases in assessed value drops from 10% to 5%.
Here's what changed and what Florida property owners should know.
What Did Florida Voters Approve?
Amendment 3 received 61.98% of the vote in the first unofficial statewide returns, clearing the 60% threshold required to amend Florida's Constitution.
For most residential property owners, there are two major changes:
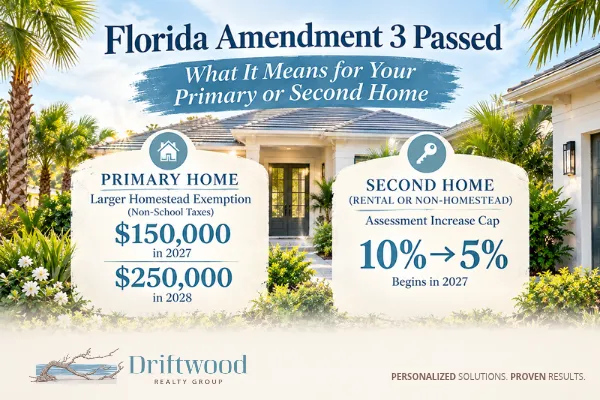
If Florida is your primary home: The homestead exemption from non-school property taxes increases to as much as $150,000 in 2027 and $250,000 in 2028 for qualifying Florida residents. Beginning in 2029, the exemption amount is adjusted annually for positive inflation growth.
If you own a second home or other non-homestead property: The annual cap on increases in the property's assessed value drops from 10% to 5% beginning in 2027.
Those are two very different benefits, so let's look at them separately.
If Florida Is Your Primary Home
For qualifying Florida homeowners who establish homestead, Amendment 3 substantially increases the amount of a home's assessed value that can be exempt from non-school property taxes.
For Florida residents covered by the new expanded exemption:
2027: Up to $150,000 of assessed value may be exempt from non-school property taxes.
2028: The exemption increases to as much as $250,000.
2029 and beyond: The exemption is adjusted annually for positive inflation growth.
That's a significant increase from Florida's current homestead exemption.
But there's an important distinction.
The Larger Exemption Does Not Apply to School Taxes
The new exemption applies to property taxes levied by taxing authorities other than school districts.
So this does not mean that the first $150,000 or $250,000 of your home's assessed value disappears from every portion of your property tax bill. School district taxes are treated differently.
That's also why you shouldn't estimate your savings simply by multiplying $150,000 or $250,000 by your total tax rate.
The actual impact will depend on your home's assessed value and the individual taxing authorities and millage rates that apply to your property.
Want to look up your own property?
Your county Property Appraiser is the best place to start for your assessed value, exemptions and homestead information.
St. Johns County: St. Johns County Property Appraiser | St. Johns County Tax Collector
Duval County: Duval County Property Appraiser | Duval County Tax Collector
December 31, 2026 Is an Important Date
One of the details that may be especially important for people moving to Florida is when they establish permanent Florida residency.
Under Amendment 3, people who maintain permanent Florida residence as of December 31, 2026 and have established or later establish homestead can qualify for the expanded exemption schedule.
People who establish permanent Florida residence on or after January 1, 2027 are treated differently.
They can still qualify for Florida's homestead exemption when otherwise eligible, but initially receive an exemption of up to $50,000 from non-school levies, adjusted for positive inflation beginning in 2028. Beginning with the fifth year of the exemption, they may become eligible for the larger exemption available to those who maintained Florida residence by December 31, 2026.
That's a meaningful distinction for someone who is already planning a move to Florida.
It isn't, however, a reason to establish residency solely to obtain a property tax benefit. Residency and homestead eligibility involve legal and tax considerations beyond real estate, so those decisions should be discussed with the appropriate professional.
What About Save Our Homes and Portability?
Florida's existing Save Our Homes benefit remains important.
For qualifying homesteaded properties, Save Our Homes limits how quickly the assessed value of a home can increase from year to year.
Florida's portability provisions can also allow eligible homeowners moving from one Florida homestead to another to transfer some of their accumulated Save Our Homes benefit to their new property.
This is one reason we caution buyers not to look at the seller's current property tax bill and assume theirs will be the same.
It may not be.
The seller may have owned the home for many years, have a substantially lower assessed value, qualify for exemptions you won't receive or have a portability benefit that is different from yours.
If Your Florida Property Is a Second Home
Second-home owners are affected by a different part of Amendment 3.
If your Florida property is not your homestead, you do not receive the new $150,000 or $250,000 homestead exemption simply because you own property here.
However, beginning January 1, 2027, Amendment 3 lowers the annual assessment-growth cap on non-homestead property from 10% to 5%.
That can matter for Florida second-home owners, particularly in areas where property values have increased substantially.
What Does the New 5% Cap Mean?
Here's an important distinction:
It limits how much the property's assessed value can increase annually. It does not guarantee that your total property tax bill can only increase by 5%.
Your final tax bill is affected by more than assessed value. Millage rates, taxing districts and other factors can change as well.
But reducing the assessment cap from 10% to 5% can slow the rate at which the assessed value of a non-homesteaded property increases over time.
For someone who plans to own a Florida second home for many years, that could become increasingly meaningful.
What If You Own a Rental Property?
The same 5% assessment limitation applies more broadly to non-homestead residential property, so Amendment 3 isn't limited to vacation or second homes.
Rental properties and other qualifying non-homestead real estate are also affected by the reduction of the assessment-growth limitation from 10% to 5%.
Again, this is a cap on increases in assessed value, not a cap on the entire tax bill.
If You're Buying a Florida Home, Don't Rely on the Seller's Tax Bill
This was good advice before Amendment 3, and it becomes even more important now.
A property's current tax bill tells you what that owner is paying under that owner's circumstances.
It doesn't necessarily tell you what you'll pay after you buy it.
A longtime owner may have accumulated years of Save Our Homes protection. A seller may have homestead or other exemptions you won't qualify for. A second home may currently be taxed differently than it will be when you make it your primary residence.
And when ownership changes, the property's assessed value can be affected under Florida's assessment rules.
When we're helping buyers compare homes, we look beyond the tax amount shown on the listing and help them identify the factors they should investigate for their particular purchase.
What Does Amendment 3 Mean If You're Selling?
Amendment 3 doesn't change the market value of your home or how we determine an appropriate listing price.
But property taxes are part of the cost of owning a home, and buyers pay attention to them.
That's especially relevant here in Northeast Florida, where someone may be comparing homes in St. Johns County and Duval County, or comparing a primary residence with a property they plan to use as a second home.
As sellers and agents, we need to be careful not to tell a prospective buyer what their future tax bill will be based solely on what the current owner pays.
Their tax situation may be very different.
So, How Much Will Amendment 3 Save You?
There isn't one answer.
Your actual savings will depend on factors including:
Whether the property is your homestead or a non-homestead property
When you established permanent Florida residency
Your property's assessed value
Your Save Our Homes history and any portability benefit
The taxing authorities that apply to your property
Local millage rates
Other exemptions for which you may qualify
That's why we'd be cautious about any headline promising that every Florida homeowner will save a particular dollar amount.
The amendment changes the rules, but the financial impact will be different for every property owner.
Want to look up your own property?
Your county Property Appraiser is the best place to start for your assessed value, exemptions and homestead information.
St. Johns County: St. Johns County Property Appraiser | St. Johns County Tax Collector
Duval County: Duval County Property Appraiser | Duval County Tax Collector
The Bottom Line
The simplest way to think about Amendment 3 is this:
If Florida is your primary home:
Qualifying homeowners may receive a substantially larger exemption from non-school property taxes, increasing to as much as $150,000 in 2027 and $250,000 in 2028.
If Florida is your second home:
You don't receive the larger homestead exemption, but the annual cap on increases in assessed value drops from 10% to 5%.
If you're planning to move to Florida:
December 31, 2026 is an important date because the amendment treats people who maintain permanent Florida residence by that date differently from those establishing residency beginning in 2027.
And whether you're buying, selling or simply trying to understand what the change means for a home you already own, remember that Florida property taxes are highly property-specific.
Your county property appraiser is the best source for information about your property's assessed value and exemptions, and tax or legal questions should be directed to the appropriate professional.
If you're considering a move in Northeast Florida, we're always happy to help with the real estate side of the equation and help you understand what questions to ask before making a decision.
Kristin & Quinton Doakes
Brokers | Driftwood Realty Group
904.826.3690